
Pune Office Leasing Rises 31.6%: Key Locations to Watch in 2026
Pune Office Leasing Rises 31.6%: Key Locations in 2026
SHARE:

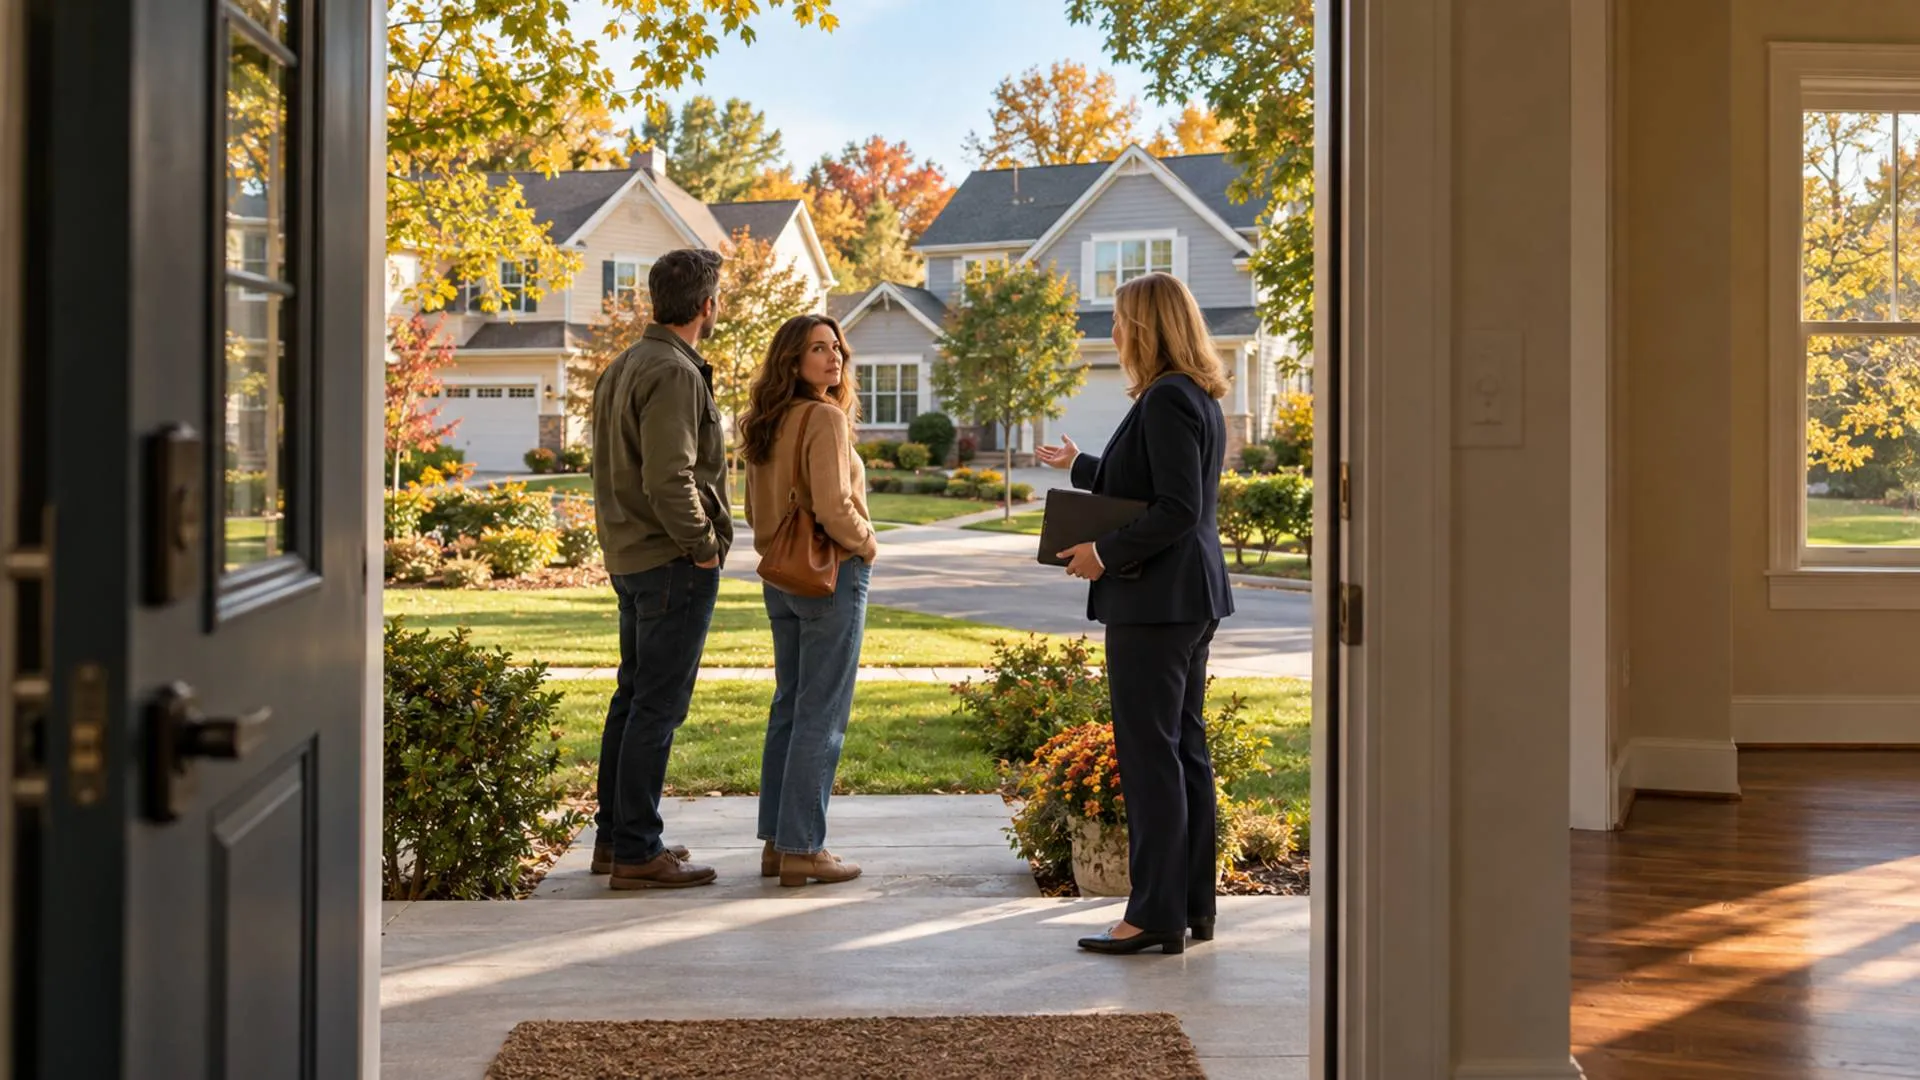
With companies pledging additional workspace, global capability centres expanding and demand continuing to be concentrated in identifiable employment hubs, Pune’s office market is proving an interesting space to invest in.
Pune saw a 31.6% YoY increase in gross leasable office space to 8.25 million sq ft between January and September 2026 making it a key consideration for investors given by JLL’s latest office market release.
Those looking to invest in Pune’s commercial property market will be looking at 2026 and asking where offices have proven to have demand and where this activity can support potential housing around the area.
Pune office leasing 2026: which locations are driving demand?
Kharadi and the wider SBD East cluster lead Pune’s office demand, followed by the western employment belt around Hinjewadi and Wakad. Baner and other established business locations also deserve attention. Corridor shares vary by quarter, so compare the reporting period before using them to shortlist property.
Pune’s Office Leasing Growth: What the Numbers Actually Measure
Pune’s office market recorded its highest-ever half-year leasing in H1 2026, according to Knight Frank’s India Real Estate report: 6.6 million sq ft, up 29% year-on-year. Campus developments in Kharadi, Hinjewadi and Baner attracted large transactions.
Meanwhile, Punekar News, reporting Knight Frank’s nine-month assessment, recorded 8.8 million sq ft, an 18% annual increase and the highest January–September total since 2018.
These figures differ from JLL’s because consultancy datasets and transaction coverage vary. They should remain separately attributed.
The same distinction applies to gross leasing and net absorption. Gross activity can include renewals and pre-commitments; net absorption measures the change in occupied space within the tracked stock.
That helps explain why NoBroker’s Q1 report, citing ANAROCK, described weaker net absorption even though subsequent reports showed strong leasing. Different measures can reveal different aspects of the market.
Kharadi Versus Hinjewadi: Which Pune Office Corridor Is Stronger?
For buyers researching the best office locations in Pune in 2026, Kharadi and Hinjewadi remain essential comparisons. However, neither represents an entire business district.
Cushman & Wakefield’s Q2 2026 Office MarketBeat recorded approximately 56% of quarterly leasing in SBD East and 33% in PBD West. Together, they contributed roughly 89%, commonly rounded to 90%.
The geographical distinction matters:
| Office cluster | Locations within Cushman & Wakefield’s classification | What deserves attention |
|---|---|---|
| SBD East | Kharadi, Mundhwa, Hadapsar, Viman Nagar, Yerawada, Nagar Road and other eastern locations | Established campuses, GCC demand and access between employment centres |
| PBD West | Hinjewadi, Wakad, Tathawade and other peripheral western locations | Technology employment, campus access and western housing catchments |
| SBD West | Baner, Aundh, Kothrud, Pashan and other western locations | Existing business activity and alternatives to the two dominant clusters |
Source: Cushman & Wakefield’s Pune submarket definitions.
The SBD East–Kharadi 56% figure is not Kharadi’s individual market share. Similarly, PBD West’s 33% cannot be assigned solely to Hinjewadi or Wakad.
The concentration also changes. Cushman & Wakefield’s Q3 2026 market update puts SBD East at approximately 71% of quarterly leasing.
For businesses, Kharadi versus Hinjewadi should therefore involve talent access, available buildings, operating costs and employee travel, not simply the latest citywide percentage.
GCC Demand and Flexible Workspaces Are Reshaping Pune Commercial Leasing
Pune commercial real estate leasing and GCC demand in 2026 are closely connected, but there is no single GCC share that applies to every period.
Cushman & Wakefield reported that global capability centres contributed approximately 52% of Q2 leasing. Its Q3 update puts their contribution at around 65%. These are quarterly snapshots.
For the first half, Savills’ Pune Office Market Watch recorded 6.4 million sq ft of Grade A gross absorption, with GCCs accounting for nearly 42%. Pune ranked third for GCC leasing among its six tracked markets. Pune GCC also highlighted those findings.
Why are global capability centres choosing Pune? Incuspaze’s office-location guide points to the talent pipeline, established technology base, workspace options and operating-cost considerations. These explain Pune’s appeal without establishing that companies are universally choosing it instead of Bengaluru or Hyderabad.
Flexible workspace and coworking demand add another layer. The Economic Times reported a 38% flex share in Pune’s Q2 office absorption within the dataset it covered. That percentage should not be treated as a full-year share.
Separately, The Times of India reported 20,900 flex seats leased in H1 2026, up 28% annually, with demand in Baner, Viman Nagar and Kharadi. Seats and square feet measure different things.
A GCC can also occupy managed workspace. GCC demand and flex-operator leasing should not automatically be added together as mutually exclusive categories.
Locations Beyond Kharadi and Hinjewadi Deserve a Closer Look
The Baner–Balewadi office corridor deserves attention for its business activity and surrounding residential catchment. Baner already appears in Knight Frank’s account of large campus transactions; it is more than an emerging-location slogan.
Kothrud also warrants investigation. Cushman & Wakefield’s Q3 report lists Gokhale Business Bay Tower B among new completions, with a SailPoint Technologies transaction in SBD West. This provides a specific office-development signal beyond the dominant eastern and peripheral western clusters.
For Kothrud and the Vanaz metro corridor, buyers should still test the route between the property, station and workplace. Station proximity alone cannot establish an office investment case.
Hadapsar, Mundhwa, Viman Nagar, Yerawada and Nagar Road also belong in an eastern shortlist.
An ICRA research summary found that Kharadi, Hinjewadi and Viman Nagar together represented 43% of Pune’s office supply as of June 2025. That is a combined stock figure, not Viman Nagar’s individual share or a 2026 leasing percentage.
ICRA also reported rental growth of approximately 3–4% annually in Hinjewadi, Viman Nagar and Yerawada between FY2020 and FY2025, compared with 4–5% in Kharadi.
What Does Office Leasing Mean for Nearby Residential Prices?
How office leasing affects residential prices in India is best understood as a chain: occupied offices can support employment, which can strengthen rental demand and influence housing preferences.
A signed office lease is not proof of an equivalent increase in jobs, rents or apartment values. Relocations, renewals, phased occupation and hybrid working affect the outcome.
For Kharadi residential investment, examine achieved apartment rents, competing supply and travel to occupied campuses. Apply the same checks to residential property near Hinjewadi IT Park and flats near Baner–Balewadi.
Cushman & Wakefield’s Q3 residential report recorded 6,272 launches in NH4 Bypass North, approximately 45% of citywide launches, led by Hinjewadi, Balewadi and Tathawade. More homes can serve employment demand while also increasing competition between landlords.
A search for a 2 BHK or 3 BHK in Wakad–Tathawade under ₹1 crore therefore needs current project quotations, rather than assumptions drawn from office growth.
For project comparisons, Mantra Properties’ Kharadi Riverside offering, Saheel Luxton in Wakad and Shubh Developers’ Tristar in Mundhwa provide different residential propositions. Mantra Mesmer’s brochure places it in Keshav Nagar, Mundhwa. Evaluate the actual commute; “office adjacency” does not guarantee returns or make Mundhwa interchangeable with Viman Nagar.
Rents, Vacancy and Metro Connectivity: The Investment Checks
Pune office rental growth of 2.7% year-on-year refers to Cushman & Wakefield’s Q2 stock-weighted rental measure. Its Q3 citywide quoted benchmark was ₹92.2 per sq ft monthly.
By comparison, Knight Frank’s Q3 assessment, reported by Punekar News, recorded average transacted rent of ₹83, up 6% annually, and 13.8% vacancy. Quoted stock averages and transacted rents are not interchangeable.
For commercial office investment in Pune’s SBD East or PBD West, investigate tenant quality, lease expiry, fit-out obligations, vacancy and net income. A Grade A campus address alone does not establish REIT eligibility or institutional investment quality.
Metro connectivity on the Hinjewadi–Shivajinagar Line 3 adds a timely factor. The Indian Express reported that passenger operations were scheduled for November 4, 2026. As of November 2, this remains a scheduled opening, not an operating service.
Which Pune Locations Should Buyers Watch Now?
Pune’s office leasing growth in 2026 puts Kharadi and wider SBD East at the centre of attention, with Hinjewadi–Wakad, Baner–Balewadi and selected established locations providing alternatives.
The best city for office-space investment in India cannot be chosen from growth alone. Even within Pune, the stronger opportunity depends on the building, tenant, entry price and surrounding supply.